Renewal-at-risk to outbound offer. Under 90 seconds.
The problem.
Rate cycles are unlocking the largest refinance window in a decade.
Tier-1 banks deploy AI propensity models months ahead of renewal to poach books from regional and mid-size institutions.
The mid-size bank doesn't lose on credit decisioning math — it loses on three operational chokepoints.
- —Fragmented borrower signal across core, LOS (Encompass, Blend, nCino), and bureau feeds.
- —Multi-day ingestion of tax docs, paystubs, appraisals, and title.
- —Retention workflows that activate after the competitor's offer has already landed in the borrower's inbox.
The Wedge — BorrowerGraph (banks) / MemberGraph (credit unions).
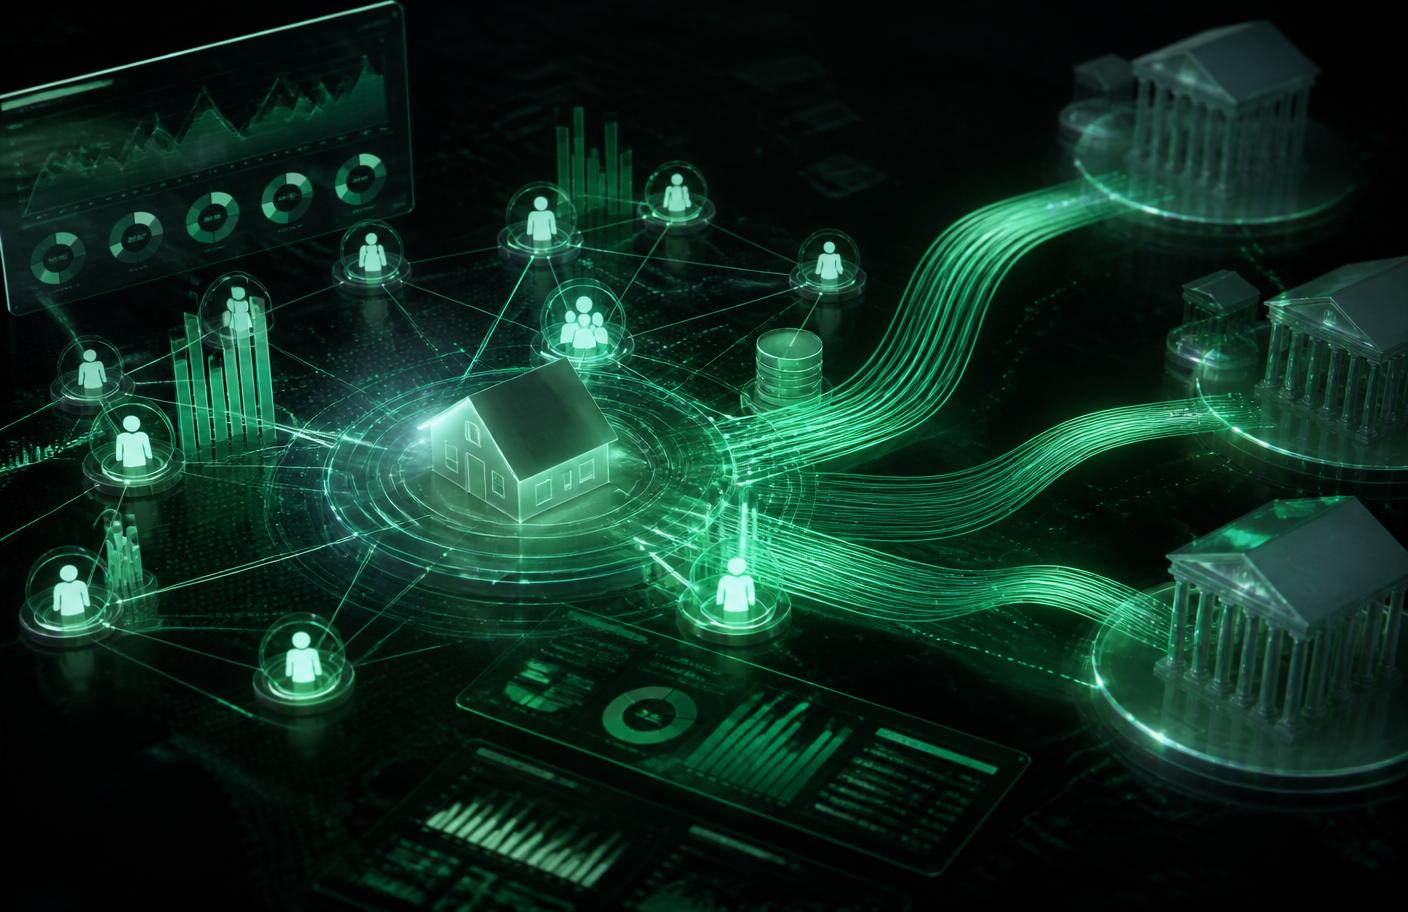
Resolved household-level entity fusing core, LOS, bureau, property, and MLS feeds — lineage-tracked, attribute-level confidence.
Event graph that surfaces life events (job change, divorce, inheritance, renewal approach) the moment they appear in any source.
Document intelligence pre-trained on mortgage paperwork — IDP throughput from days to minutes.
Any propensity, pricing, or retention model the bank runs becomes materially more accurate against the resolved entity than against raw core data.
Engineering wrap.
Agentic orchestration consumes the renewal-at-risk signal, pulls the resolved entity, parses the document bundle, runs explainable pricing, and drops a personalized offer into the bank's digital channel and into the loan officer's queue — under 90 seconds from trigger to outbound.
Credit-union variant — MemberGraph.
The same pattern, tuned to credit-union systems:
- —Symitar
- —Corelation Keystone
- —Jack Henry CUbase
- —MeridianLink
- —Origence
- —dealer feeds
Indirect auto recapture runs on the same substrate.
The workflow.
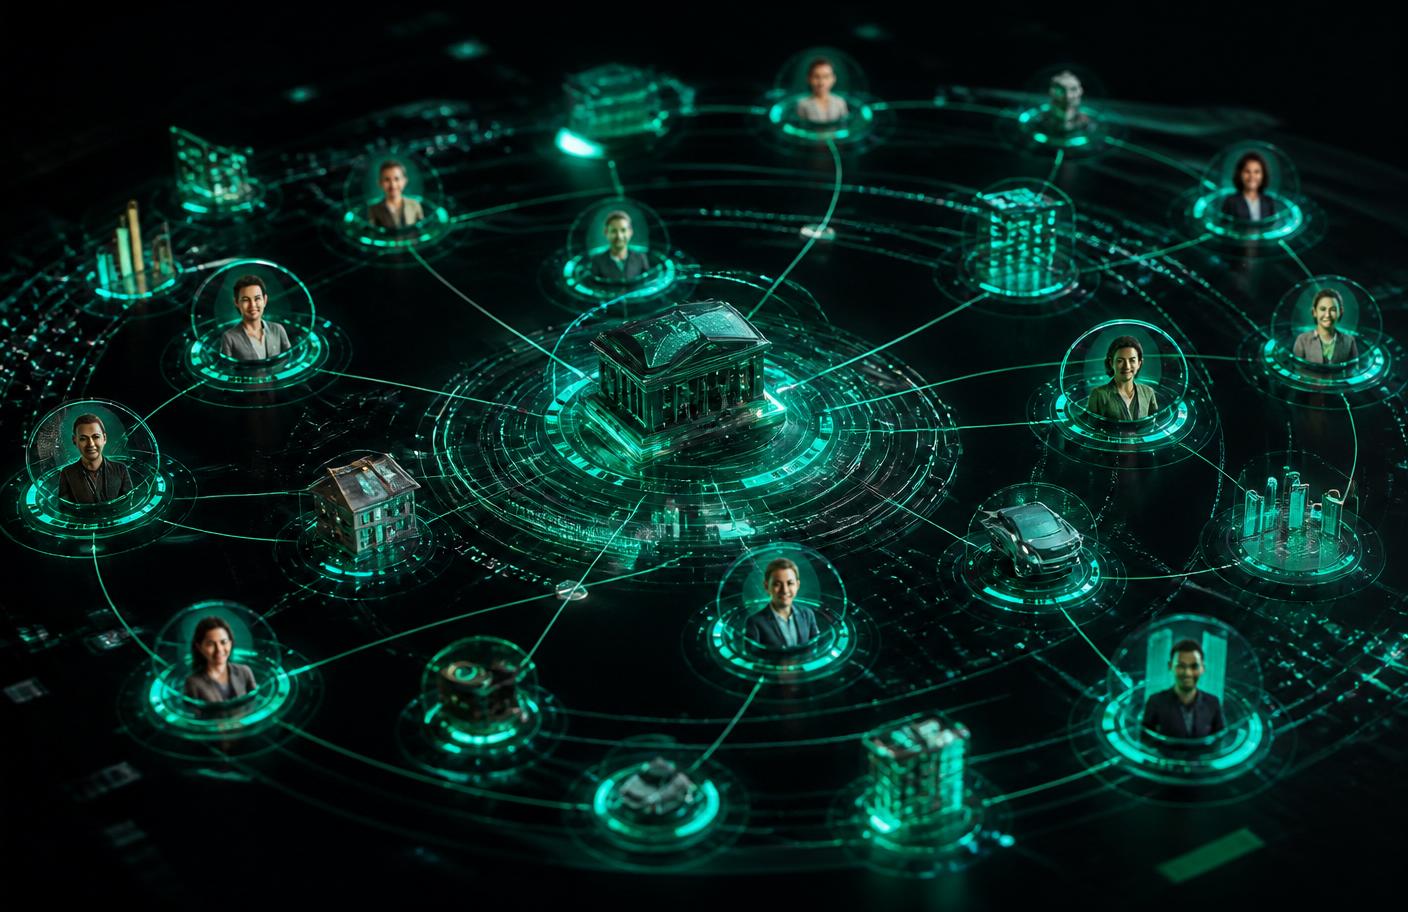
Signal to offer — one substrate, seven stops.
- CustomerDigital channel
- Core BankingSystem of record
- LOSEncompass / Blend / nCino
- MLSProperty feeds
- BorrowerGraphResolved entity
- Pricing EngineExplainable model
- OfferUnder 90s